Corporate Bond Market Recovers in Scale but Remains Heavily Reliant on the Banking System. Vietnam’s corporate bond market has recovered significantly in size, but it remains heavily dependent on the banking system. According to Ms. Nguyen Thi Trieu, Founder and Deputy CEO of Optima Wealth Partners, unlocking medium- and long-term capital flows requires expanding the role of institutional investors, particularly the insurance sector.
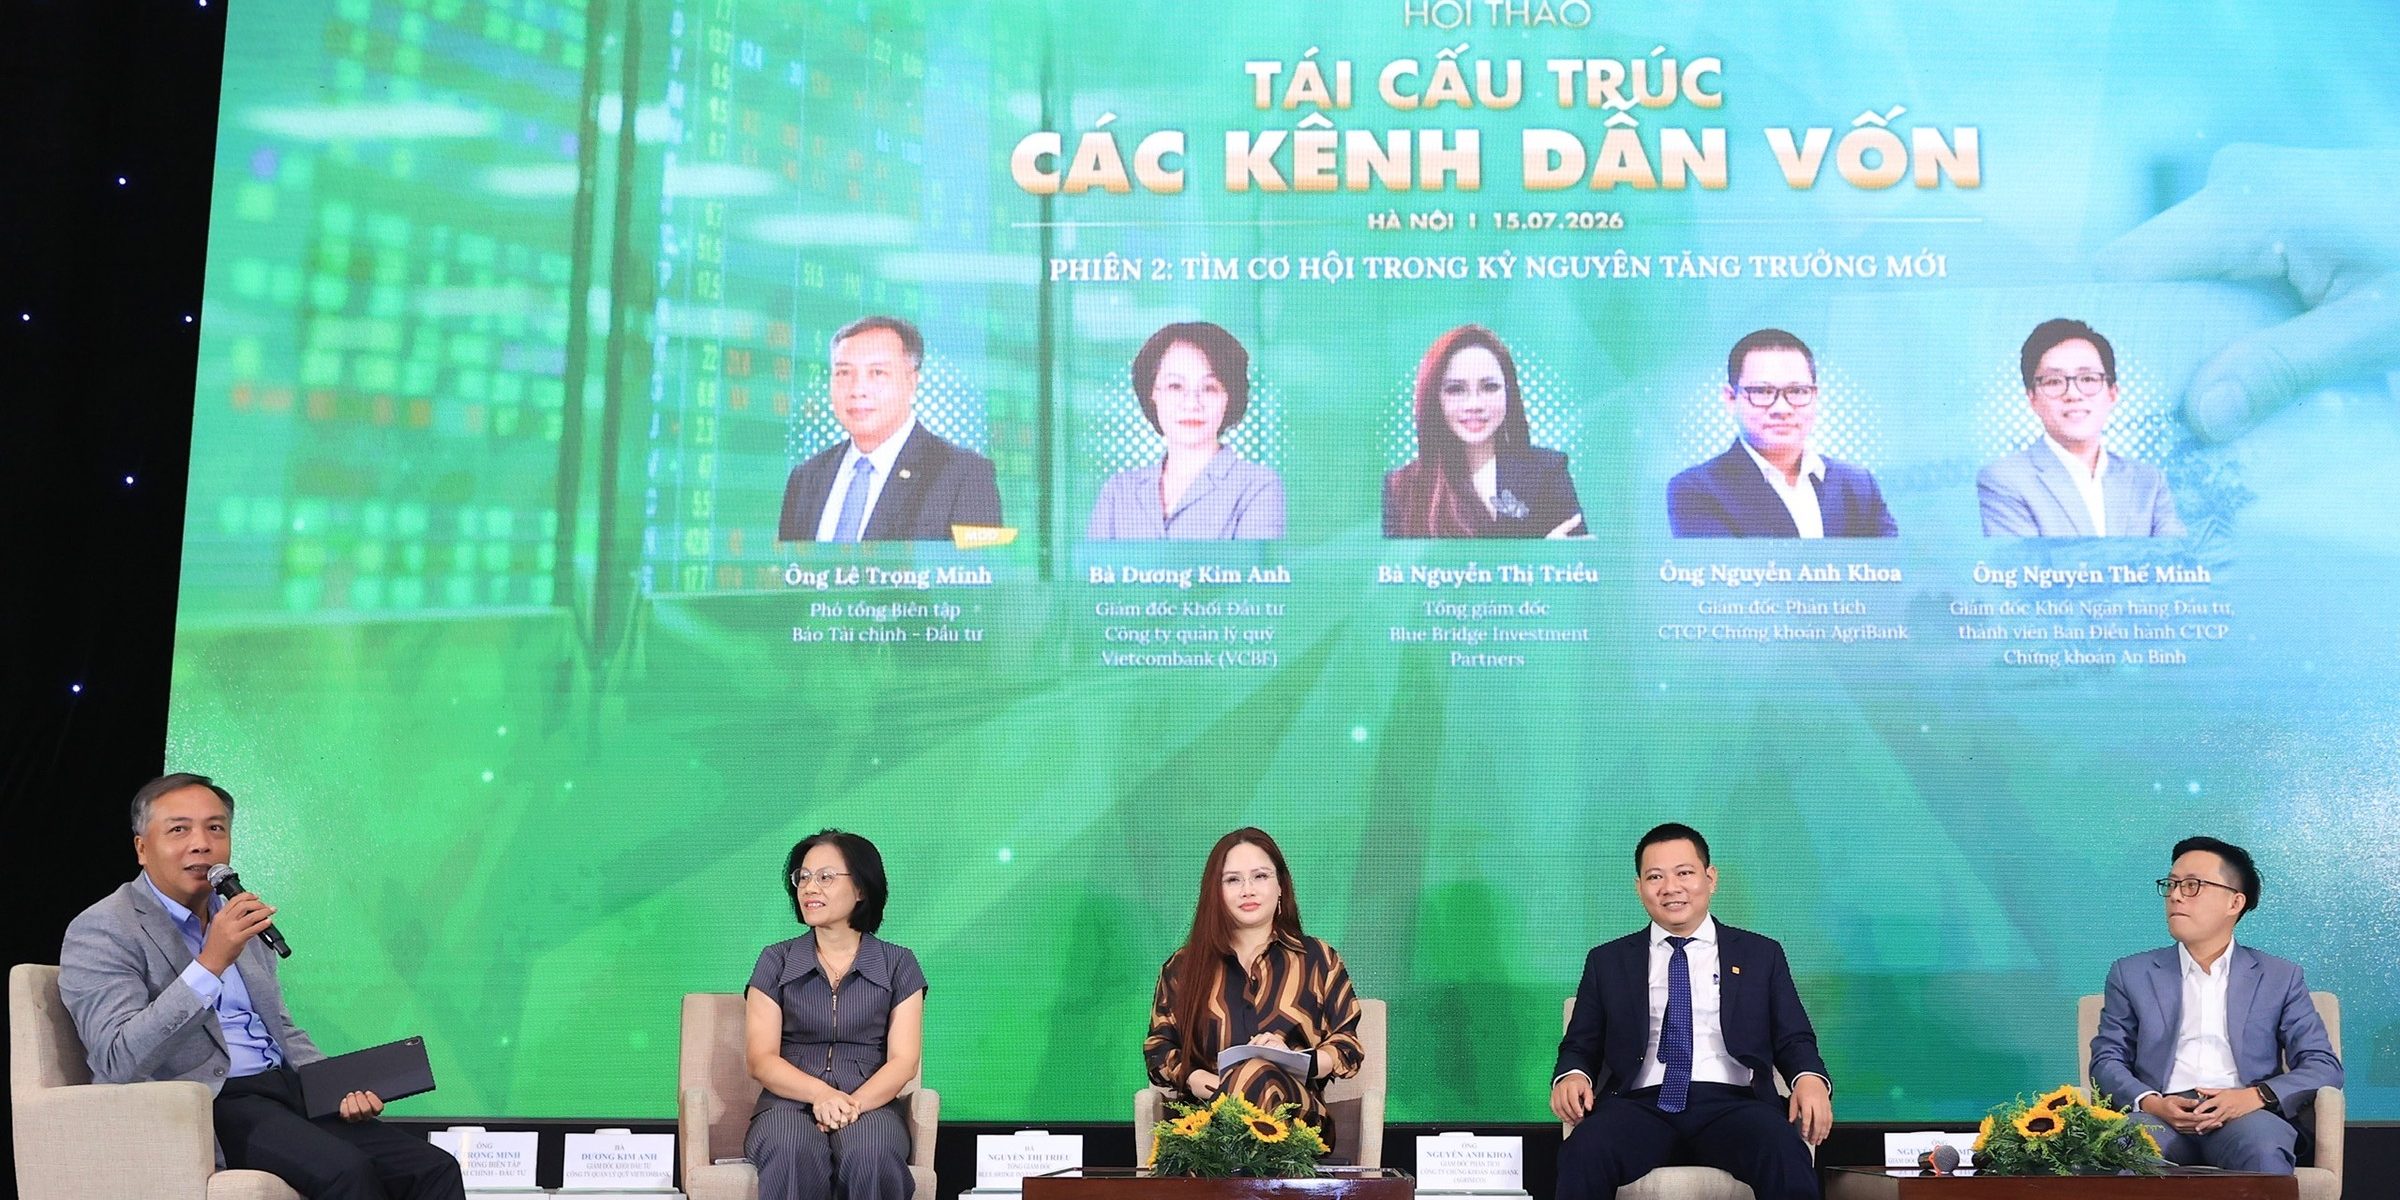
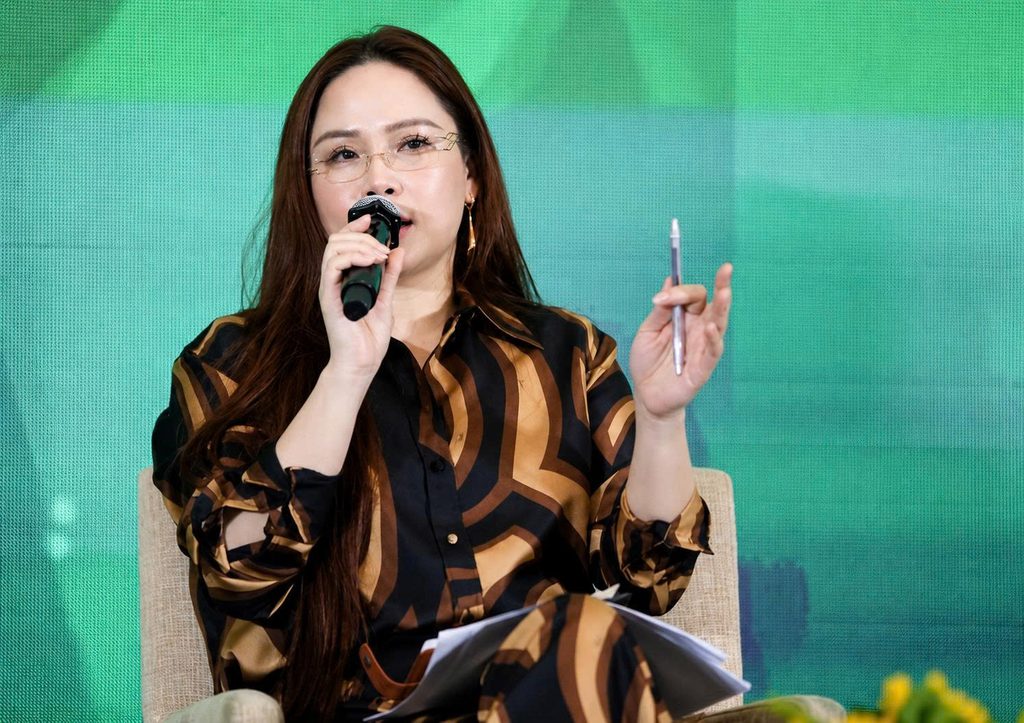
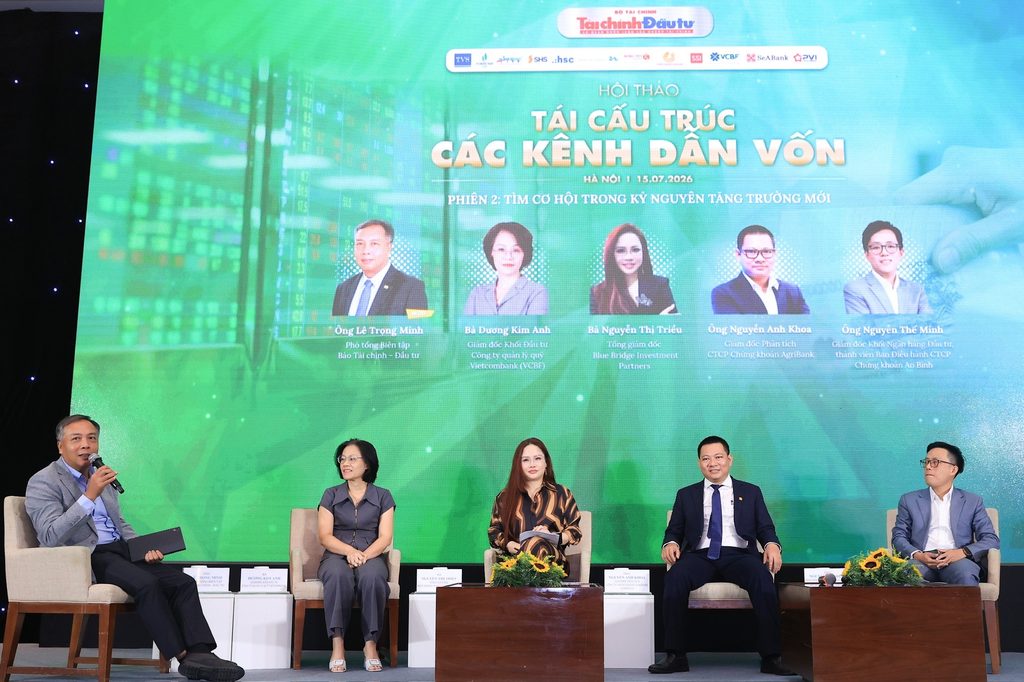
Speaking at the second discussion session of the seminar “Restructuring Capital Channels,” hosted by Vietnam Investment Review (VIR) on 15 July, Ms. Nguyen Thi Trieu, Deputy CEO of Optima Wealth Partners, said that the size of the corporate bond market has recovered considerably since the crisis period. However, a closer look at the market’s structure reveals a very heavy dependence on the banking system.
According to Ms. Trieu, around 80% of bonds currently issued come from banks and real estate companies, while 60–70% of buyers are also banks. This means the bond market, in essence, still revolves around the bank credit sector and has yet to achieve its goal of diversifying capital-raising channels for the economy.
“We talk about reducing dependence on bank credit, yet the main players in the bond market today are still banks. As a result, neither supply nor demand has been truly diversified,” Ms. Trieu observed.
She noted that what matters is not only expanding the market’s scale, but also directing bond capital into sectors capable of generating long-term added value for the economy — similar to how credit is directed toward priority industries.
Unlocking Insurance Capital for Infrastructure
Ms. Trieu particularly emphasized the development of an infrastructure bond market. According to the Deputy CEO of Optima Wealth Partners, the government’s ongoing efforts to build a legal framework for PPP bonds are a very positive signal, given Vietnam’s still-substantial infrastructure investment needs. However, infrastructure projects are characterized by long payback periods and relatively low returns, which makes fundraising challenging.
“Developing a sustainable bond market requires diversifying both supply and demand, rather than leaving banks to serve as both the main issuers and the main investors.”
— Ms. Nguyen Thi Trieu, Founder & Deputy CEO, Optima Wealth Partners
Meanwhile, capital from insurance companies — particularly life insurers — carries very long tenors, from 25 to 30 years, which aligns well with the investment cycle of infrastructure projects.
“I believe this is a very suitable source of capital for investing in infrastructure bonds. What is still missing are credit enhancement mechanisms that would help insurance companies manage risk when investing in long-tenor bonds,” Ms. Trieu said.
She also noted that most of the capital held by insurance companies and Vietnam Social Security is currently invested mainly in government bonds. If an appropriate mechanism were in place to channel this capital directly into infrastructure bonds, the economy would gain an additional source of long-term funding without adding to public debt pressure.
Individual Investors Should Not Be Encouraged to Invest In Individual Corporate Bonds
Asked how to bring individuals back into corporate bond investment in a meaningful way, Ms. Trieu expressed a clear view: individual investors should not be encouraged to participate extensively in the market for individually issued corporate bonds.
According to her, this asset class requires the ability to assess credit risk, analyze a company’s financial health, and evaluate repayment capacity — capabilities that only professional or institutional investors are typically equipped to handle.
“I do not encourage individual investors to participate in the market for individually issued corporate bonds. What needs to be done is to build up the institutional investor base, so the market can operate in a more professional and sustainable way,” said the Deputy CEO of Optima Wealth Partners.
Legal Barriers Need to Be Removed
Beyond expanding institutional capital, Ms. Trieu also pointed to a number of regulations that still need to be refined.
One example is the mechanism for securitizing or refinancing infrastructure projects that are already operational. According to her, many such projects have generated stable cash flows, yet insurance companies are still not permitted to invest in them because they are classified as debt-restructuring bonds.
Ms. Trieu argued that projects should be assessed based on the underlying nature of their risk rather than solely on the legal form of the bond instrument. If this bottleneck were removed, insurance capital could quickly begin financing infrastructure projects that are already operating stably.
Upgrading the Sovereign Credit Rating to Lower the Cost of Capital
Turning to international capital raising, Ms. Trieu noted that since the start of the year, many Vietnamese banks and enterprises have stepped up issuance of international bonds, reflecting growing demand for access to foreign capital.
However, the biggest barrier at present is Vietnam’s sovereign credit rating. Even when a company has strong financials, its credit rating remains capped by the sovereign rating ceiling, which raises the cost of capital, as issuers must rely on additional international credit guarantee instruments.
According to Ms. Trieu, Vietnam has already met most of the quantitative criteria for reaching investment-grade status. What remains are qualitative factors and the ongoing process of engagement with credit rating agencies.
“If Vietnam achieves investment-grade status, Vietnamese enterprises will find it far easier to raise capital internationally, and the cost of capital will fall significantly,” Ms. Trieu emphasized. Beyond capital market solutions, Ms. Trieu also said that capital flows in the coming period will continue to favor sectors where Vietnam holds a competitive advantage, such as import-export, infrastructure, and logistics, while also noting that tourism has considerable room to grow as Vietnam becomes an increasingly attractive destination on the global tourism map.